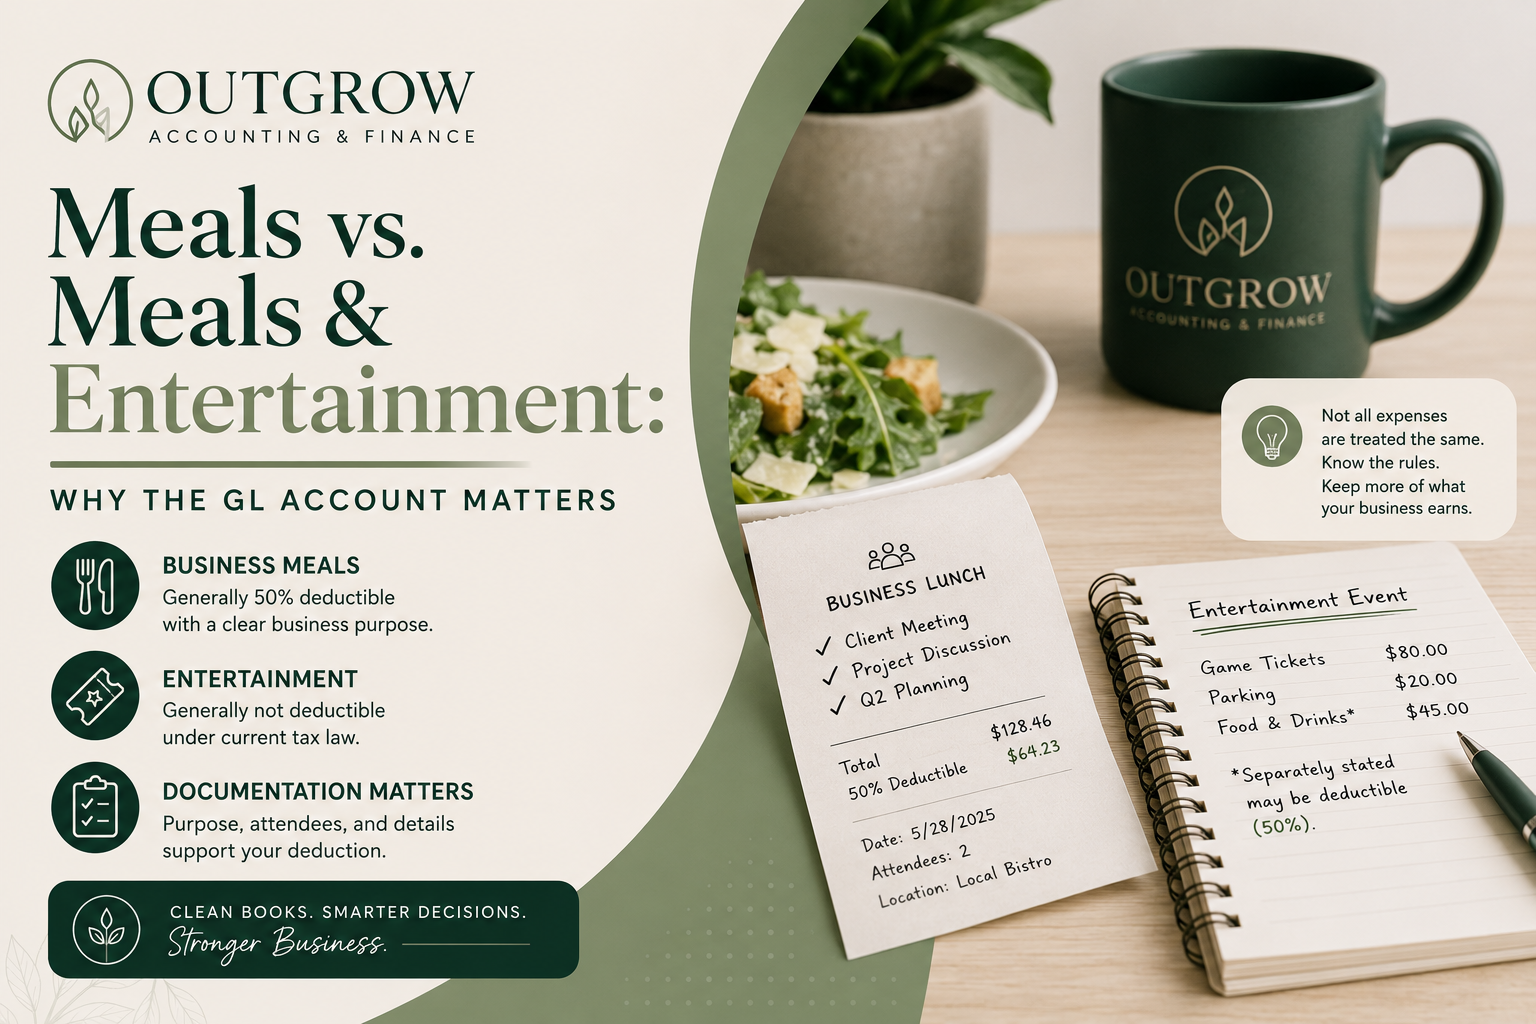
Meals and entertainment can be one of those accounting categories that feels simple until it is time to review the books. Understanding tax deductions in terms of meals and entertainment is essential for accurate accounting.
A client takes someone to lunch. A team member buys coffee during a business meeting. The company hosts a holiday party. A business owner takes a potential client to a game and buys food while they are there.
At first glance, these may all feel like “business meals” or “client expenses.” But from an accounting and tax perspective, they may not be treated the same way.
That is why some businesses choose to have more than one general ledger account. One may be called Meals and another may be called Meals and Entertainment or Entertainment. The purpose is not to make the chart of accounts more complicated. The purpose is to make sure expenses are categorized correctly before tax time.
Because not every meal is treated the same.
Why Meals and Entertainment Get Confusing
For years, many businesses grouped meals and entertainment together. That made sense when certain entertainment expenses were partially deductible.
However, the rules changed under the Tax Cuts and Jobs Act. The IRS explains that the TCJA generally eliminated the deduction for expenses related to entertainment, amusement, or recreation: IRS: Tax Cuts and Jobs Act – Businesses.
That means the difference between a meal and entertainment matters.
A business lunch may be partially deductible.
A sporting event may not be deductible.
Food purchased separately at that sporting event may still have a different treatment than the ticket itself.
This is why it is helpful to separate these expenses in your accounting system instead of treating everything as one bucket.
Why Some Meals Are Only 50% Deductible
Most qualifying business meals are subject to a 50% deduction limit.
The IRS states that the deduction for business meals is generally limited to 50% of the unreimbursed cost: IRS Topic No. 511: Business Travel Expenses. IRS Publication 463 also explains rules around travel, gift, car, and meal expenses, including the 50% limitation: IRS Publication 463.
In plain English, this means that even if the meal is a valid business expense, the business may only be able to deduct half of it for tax purposes.
For example, if you take a client to lunch and spend $100, the expense may still be recorded in your books as $100. But when the tax return is prepared, only $50 may be deductible if it falls under the 50% limitation.
This is one reason clean bookkeeping matters. Your books should show the actual expense. The tax treatment may be adjusted later by your CPA.
What Makes a Business Meal Deductible?
A business meal generally needs to have a clear business purpose.
That does not mean every meal with another person automatically qualifies. The meal should be ordinary and necessary for the business, not lavish or extravagant, and connected to a business discussion, business travel, a client meeting, or another valid business purpose.
The IRS uses the concept of ordinary and necessary when evaluating business expenses. Ordinary means common and accepted in your trade or business. Necessary means helpful and appropriate for your business. The IRS explains this standard in its business expense guidance: IRS: Guide to Business Expense Resources.
A deductible business meal should usually answer questions like:
Who was there?
What was the business purpose?
What was discussed?
How does this relate to the business?
Was the amount reasonable?
A receipt alone does not always tell the full story. Good documentation matters because the business purpose is what supports the deduction.
What About Meals During Entertainment?
This is where the separate GL accounts become especially helpful.
Entertainment is generally not deductible. That includes expenses related to entertainment, amusement, or recreation. However, the IRS has clarified that food and beverages provided during an entertainment event may still be deductible if they are purchased separately from the entertainment or if the cost is stated separately on the bill, invoice, or receipt: IRS: Enhanced Business Meal Deduction Guidance.
For example, if you take a client to a basketball game, the tickets are generally entertainment and would not be deductible.
If you buy food and drinks separately at the game, and those costs are separately stated, the food and beverage portion may be treated differently than the tickets.
This is why tossing everything into one “Meals and Entertainment” account can create confusion. It may make it harder for your CPA to determine what is deductible, what is 50% deductible, and what should be excluded.
Why You May Want Separate GL Accounts
Having separate accounts for meals and entertainment helps keep the books cleaner.
A simple setup may include accounts such as:
Meals – 50% Deductible
Meals – 100% Deductible
Entertainment – Nondeductible
Employee Events or Team Meals
Travel Meals
The exact setup depends on the business, industry, and CPA preference. The goal is not to overcomplicate the chart of accounts. The goal is to avoid lumping expenses together that have different tax treatment.
This matters because bookkeeping and tax preparation serve different purposes.
Bookkeeping shows what actually happened in the business.
Tax preparation determines what portion of those expenses can be deducted under current tax rules.
When the general ledger is organized well, the tax process is cleaner, faster, and less likely to require backtracking through receipts.
Examples of Common Meal and Entertainment Categories
A client lunch with a clear business purpose is often recorded as a business meal and may be subject to the 50% limitation.
A meal while traveling for business may also be subject to the 50% limitation, assuming the travel qualifies as business travel.
A company holiday party or employee appreciation event may have different treatment than a client meal, which is why many businesses track employee events separately.
Leave a Reply