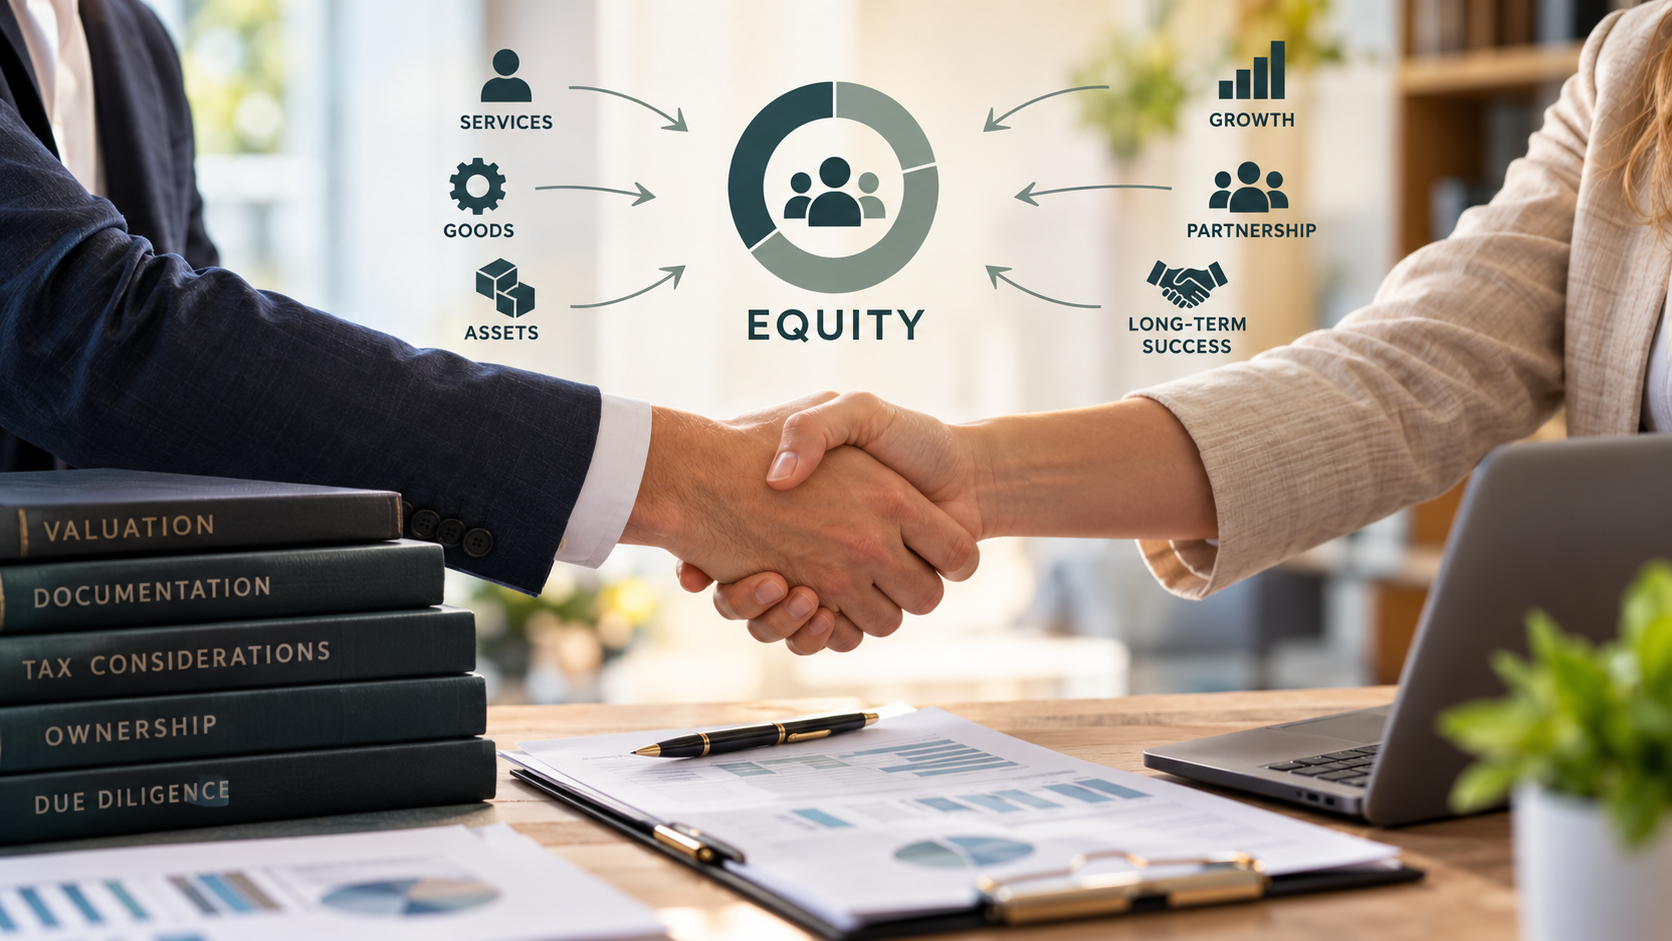
Giving equity in exchange for services, goods, or assets can be a powerful strategy for a growing business.
Instead of using cash, a company may offer ownership to a consultant, employee, supplier, investor, or other contributor in exchange for work, equipment, intellectual property, inventory, or another valuable asset.
As a result, the business can preserve cash while creating alignment between the contributor and the company’s long-term success.
However, giving away company equity is not the same as writing a check.
Once ownership changes hands, the transaction can affect company valuation, taxes, voting rights, financial statements, the cap table, future fundraising, and the economics of every current owner.
Therefore, before issuing equity, business owners need to understand exactly what they are giving, what they are receiving, and how they arrived at the value on both sides of the transaction.
How Do You Value a Company Before Giving Away Equity?
One of the first questions in any equity transaction should be:
What is the company worth?
Without a reasonable company valuation, it becomes difficult to determine whether an equity exchange makes financial sense.
For example, suppose someone contributes $100,000 of equipment in exchange for 10% ownership. On the surface, that transaction may imply approximately a $1 million company valuation.
However, an implied valuation does not automatically mean the business is actually worth $1 million.
Instead, management should support the valuation using the economics of the business and the specific circumstances surrounding the transaction.
Depending on the company, valuation may consider:
- Historical revenue
- Profitability
- EBITDA or adjusted earnings
- Cash flow
- Assets and liabilities
- Recurring revenue
- Customer concentration
- Intellectual property
- Growth rate
- Market opportunity
- Comparable companies
- Comparable transactions
- Business risk
- Existing debt
- Future capital requirements
An established business will generally have more historical financial information to support its valuation. In contrast, an early-stage business may rely more heavily on growth expectations, market opportunity, and other forward-looking factors.
Regardless of the methodology, management should make the valuation deliberate, supportable, and well documented.
What Does the Ownership Percentage Actually Include?
Business owners often start with a question like:
“Should I give them 5% or 10%?”
Yet the percentage represents only part of the conversation.
More importantly, you need to define exactly what rights come with that ownership.
For example, does the person receiving equity receive:
- Voting rights?
- Profit distributions?
- Rights to proceeds if the business sells?
- Board representation?
- Information rights?
- Preferred distributions?
- Protection against future dilution?
- Rights to participate in future capital raises?
Two people can each own 10% of a company while holding very different economic and governance rights.
For that reason, the operating agreement, shareholder agreement, equity issuance documents, and other governing documents matter just as much as the ownership percentage.
Giving Equity in Exchange for Services
Companies commonly use equity in exchange for professional services.
For instance, businesses may offer equity to executives, consultants, employees, advisors, contractors, founders, or strategic partners.
This arrangement can be especially appealing when the company wants to preserve cash. At the same time, equity compensation can create tax consequences for both the company and the recipient.
Before issuing ownership for services, consider questions such as:
- What is the fair market value of the equity?
- Will the recipient receive all of the ownership immediately?
- Will the ownership follow a vesting schedule?
- Will the company treat the equity as compensation?
- Do payroll or withholding requirements apply?
- Could an 83(b) election apply?
- Will the person receive stock, units, options, a capital interest, or a profits interest?
- What happens if the person leaves?
- Can the company repurchase the ownership?
Because the answers depend heavily on the entity structure and transaction terms, the company should involve its CPA and attorney before issuing the equity.
Should Equity for Services Vest Over Time?
For many service arrangements, transferring the full ownership percentage on day one can create unnecessary risk.
Instead, a vesting arrangement allows someone to earn ownership over time or after completing specific milestones.
For example, a company might structure equity as:
- 25% vesting each year for four years
- Monthly vesting over 36 or 48 months
- Equity earned after specific revenue milestones
- Ownership earned after completing a project
- Equity subject to repurchase if the person leaves
Consider what could happen if you give someone 10% of your company immediately and that person leaves six months later.
Without appropriate agreements, a former service provider could remain a permanent owner even though they no longer contribute to the business.
Therefore, a thoughtfully designed vesting arrangement can help align the ownership earned with the value the recipient actually contributes.
Giving Equity in Exchange for Equipment or Other Assets
Businesses can also issue equity in exchange for tangible or intangible assets.
These assets may include:
- Vehicles
- Machinery
- Equipment
- Real estate
- Inventory
- Furniture
- Software
- Patents
- Trademarks
- Customer lists
- Intellectual property
Before exchanging ownership for an asset, determine what the asset is actually worth.
In particular, do not automatically assume that the contributor’s original purchase price represents today’s value.
Instead, consider factors such as:
- Fair market value
- Original cost
- Adjusted tax basis
- Condition
- Useful life
- Existing depreciation
- Outstanding loans
- Liens
- Ownership
- Whether the asset is currently in service
For significant or unusual assets, the company may also want an independent appraisal.
Additionally, determine whether the contributor will transfer the asset free and clear.
For example, an $80,000 piece of equipment with a $60,000 loan attached does not necessarily provide $80,000 of net economic value to the company.
Fair Market Value vs. Tax Basis vs. Book Value
One of the most important parts of an equity-for-assets transaction is understanding that fair market value, tax basis, and book value can represent three different numbers.
Consider this example:
Original asset cost: $100,000
Adjusted tax basis: $30,000
Current fair market value: $60,000
So, what is the asset worth?
The answer depends on why you need the number.
For example, fair market value may help determine the economics of the equity transaction. Meanwhile, tax basis can affect the tax treatment, while book value can influence how the business reflects the asset in its accounting records.
Furthermore, the parties could negotiate yet another value in the equity agreement.
Because these numbers can differ significantly, businesses should avoid recording a journal entry based solely on the number discussed between the owners. Instead, coordinate with the CPA to determine the appropriate accounting and tax treatment.
Giving Equity in Exchange for Goods or Inventory
A business may also exchange equity for goods or inventory.
For example, a supplier could provide $50,000 of product in exchange for an ownership stake.
Before agreeing to that transaction, management should consider several questions:
- What is the actual fair value of the inventory?
- Can the business realistically sell or use it?
- Does the stated value represent retail price, wholesale cost, replacement cost, or something else?
- What would the company pay for the same inventory in cash?
- What ownership percentage will the supplier receive?
- What company valuation does that percentage imply?
Suppose a company gives away 10% ownership for $50,000 of inventory. Economically, that transaction may imply a company value of approximately $500,000.
Consequently, the business should determine whether that implied valuation makes sense before completing the deal.
A useful question is:
If we were paying cash for these goods, would we willingly pay this amount?
If not, using equity instead of cash does not automatically turn it into a better transaction.
Equity Is Not Free
Growing companies sometimes use equity because it eliminates the need to write a check today.
Nevertheless, equity can ultimately become far more expensive than cash.
Suppose someone provides $50,000 of services.
The business could pay $50,000 in cash, or it could give that person 5% ownership.
At a $1 million company valuation, those amounts may initially appear similar.
Now imagine the company eventually sells for $20 million.
Before considering dilution, preferences, transaction costs, and other terms, that 5% interest could represent $1 million.
The services did not necessarily become worth $1 million. The ownership did.
In some situations, that outcome makes perfect sense because the person receiving the equity helped create a meaningful portion of the company’s future value.
In other situations, the founders may eventually realize they traded away far more value than they intended.
Therefore, ask this question before completing the transaction:
If this company becomes significantly more valuable, will we still believe this was a fair deal?
How Equity Dilution Affects Existing Owners
Whenever a company issues new equity, existing owners need to understand how the transaction changes their ownership percentages.
This change is commonly referred to as dilution.
For example, suppose two founders each own 50% of a company. After the company issues new ownership to a third person, the two founders may own less than 50% each.
Because of this, the cap table should clearly show ownership before and after the transaction.
At a minimum, businesses should track:
- Owner names
- Shares or units
- Ownership percentages
- Classes of ownership
- Options
- Warrants
- Convertible instruments
- Vesting
- Potential future dilution
Additionally, the agreement should make clear whether the negotiated ownership percentage applies before or after the new equity issuance.
That distinction can materially change the economics of the deal.
What Documentation Is Needed When Issuing Equity?
Never rely solely on a handshake, email, or verbal agreement for an equity transaction.
Instead, create documentation that clearly explains what each party contributed and what each party received.
Depending on the legal structure and transaction, documentation may include:
- Business valuation support
- Equity issuance agreement
- Membership interest agreement
- Stock purchase agreement
- Asset contribution agreement
- Board approval
- Member or shareholder approval
- Updated operating agreement
- Updated shareholder agreement
- Updated capitalization table
- Vesting agreement
- Buyback or repurchase provisions
- Bill of sale
- Asset appraisal
- Asset ownership documentation
- Titles
- VINs or serial numbers
- Intellectual property assignment
- Contractor or employment agreement
- Applicable tax elections
- Debt or lien documentation
Ultimately, the documentation should clearly answer five questions:
What did the company receive?
What was it worth?
What ownership did the company provide in return?
When did the transaction take effect?
What rights came with that ownership?
Clear documentation can prevent significant legal, accounting, ownership, and tax problems later.
Make Sure the Accounting Matches the Legal Documents
Problems often arise when different parts of the company tell different versions of the same transaction.
For example, the legal agreement may show one value, while the cap table reflects another. Meanwhile, QuickBooks may contain a different amount entirely, and the CPA may receive something else at year-end.
Eventually, someone has to reconcile those differences.
To avoid that situation, the finance team should clearly understand:
- What asset, good, or service did the company receive?
- What equity did the company issue?
- What value did the parties assign to each side?
- When did the transaction take effect?
- Did the company assume debt?
- What belongs on the balance sheet?
- Which equity account should the company use?
- Does an asset require depreciation or amortization?
- What useful life applies?
- Are there book-to-tax differences?
- Does any portion represent compensation expense?
Ideally, the legal documents, accounting records, tax reporting, and capitalization table should all tell the same economic story.
When Should You Get an Independent Business Valuation?
Not every equity transaction requires a full formal valuation report.
However, as the size or complexity of the transaction increases, independent valuation support may become more valuable.
For example, professional valuation assistance may make sense when:
- The company will transfer a significant ownership percentage
- Existing owners disagree about value
- New investors are involved
- The company owns substantial intangible assets
- The company uses equity for employee compensation
- A related party participates in the transaction
- The transaction could create significant tax consequences
- The business is preparing for financing or a future sale
- The company has experienced rapid growth
- The company plans to exchange equity for a high-value asset
Even when management does not obtain a formal valuation, it should still document how it determined the agreed company value.
Your CFO, CPA, and Attorney Have Different Roles
An equity transaction crosses several professional disciplines.
First, your CFO or financial advisor can analyze the economics, model dilution, evaluate valuation assumptions, and determine how the proposed exchange could affect the business financially.
Next, your CPA can help determine the appropriate tax and accounting treatment.
Finally, your attorney can structure the ownership transfer, prepare or review the agreements, and confirm that the transaction aligns with the company’s governing documents.
Although those responsibilities overlap in places, the professionals are not interchangeable.
For instance, a CFO may identify that giving away 10% of the company for a particular asset creates an unfavorable financial tradeoff. At the same time, a CPA may identify tax consequences, while an attorney addresses the rights attached to the ownership.
For that reason, the strongest equity transactions usually involve coordination across finance, accounting, tax, and legal.
Questions to Ask Before Giving Away Company Equity
Before finalizing an equity-for-services, goods, or assets transaction, business owners should be able to answer:
- What is the company worth today?
- How did we determine that valuation?
- What is the service, asset, property, or inventory actually worth?
- What ownership percentage will the recipient receive?
- Does that percentage apply before or after the transaction?
- What voting and economic rights come with the equity?
- Will the equity vest?
- What happens if the relationship ends?
- How will the transaction dilute existing owners?
- What tax consequences could arise?
- How will we record the transaction?
- How will the cap table change?
- What documentation supports the transaction?
- Have the CPA and attorney reviewed the structure?
- If the company becomes significantly more valuable, will the transaction still make sense?
If management cannot answer these questions clearly, the transaction may need more work before the parties finalize it.
Equity Should Be Treated as a Valuable Business Asset
Giving equity in exchange for services, goods, or assets can absolutely make sense.
For example, it can conserve cash, attract talented people, bring valuable resources into the company, and align contributors with the organization’s long-term success.
However, business owners should never treat equity as free currency.
For many growing businesses, ownership may eventually become the most valuable asset the founders possess.
Therefore, before giving it away, understand the company’s value, the value of what the company will receive, the ownership rights being transferred, the dilution created, and the accounting and tax implications of the transaction.
The goal should not simply be to answer:
“How much equity should we give them?”
Instead, ask:
“What are we exchanging, what is each side worth, and does this transaction make financial sense for the business and its owners?”
Ultimately, that type of decision deserves thoughtful financial modeling, proper documentation, and coordination between your CFO, CPA, and attorney.
Considering Giving Equity in Your Business?
Before transferring ownership, make sure you understand what your business is worth, what you will receive in return, and what the transaction could mean for your financials, existing owners, and future company value.
Outgrow Accounting & Finance helps business owners evaluate the financial side of major decisions, model ownership and dilution scenarios, understand the impact on their financial statements, and work alongside their CPA and attorney so the numbers support the strategy.
More than numbers. We grow with you.
This article is intended for general educational purposes and should not be considered tax, accounting, valuation, investment, or legal advice. Equity transactions can have significant consequences depending on the entity structure and specific circumstances. Consult your CPA, attorney, and appropriate financial professionals before issuing or transferring company ownership.
Leave a Reply