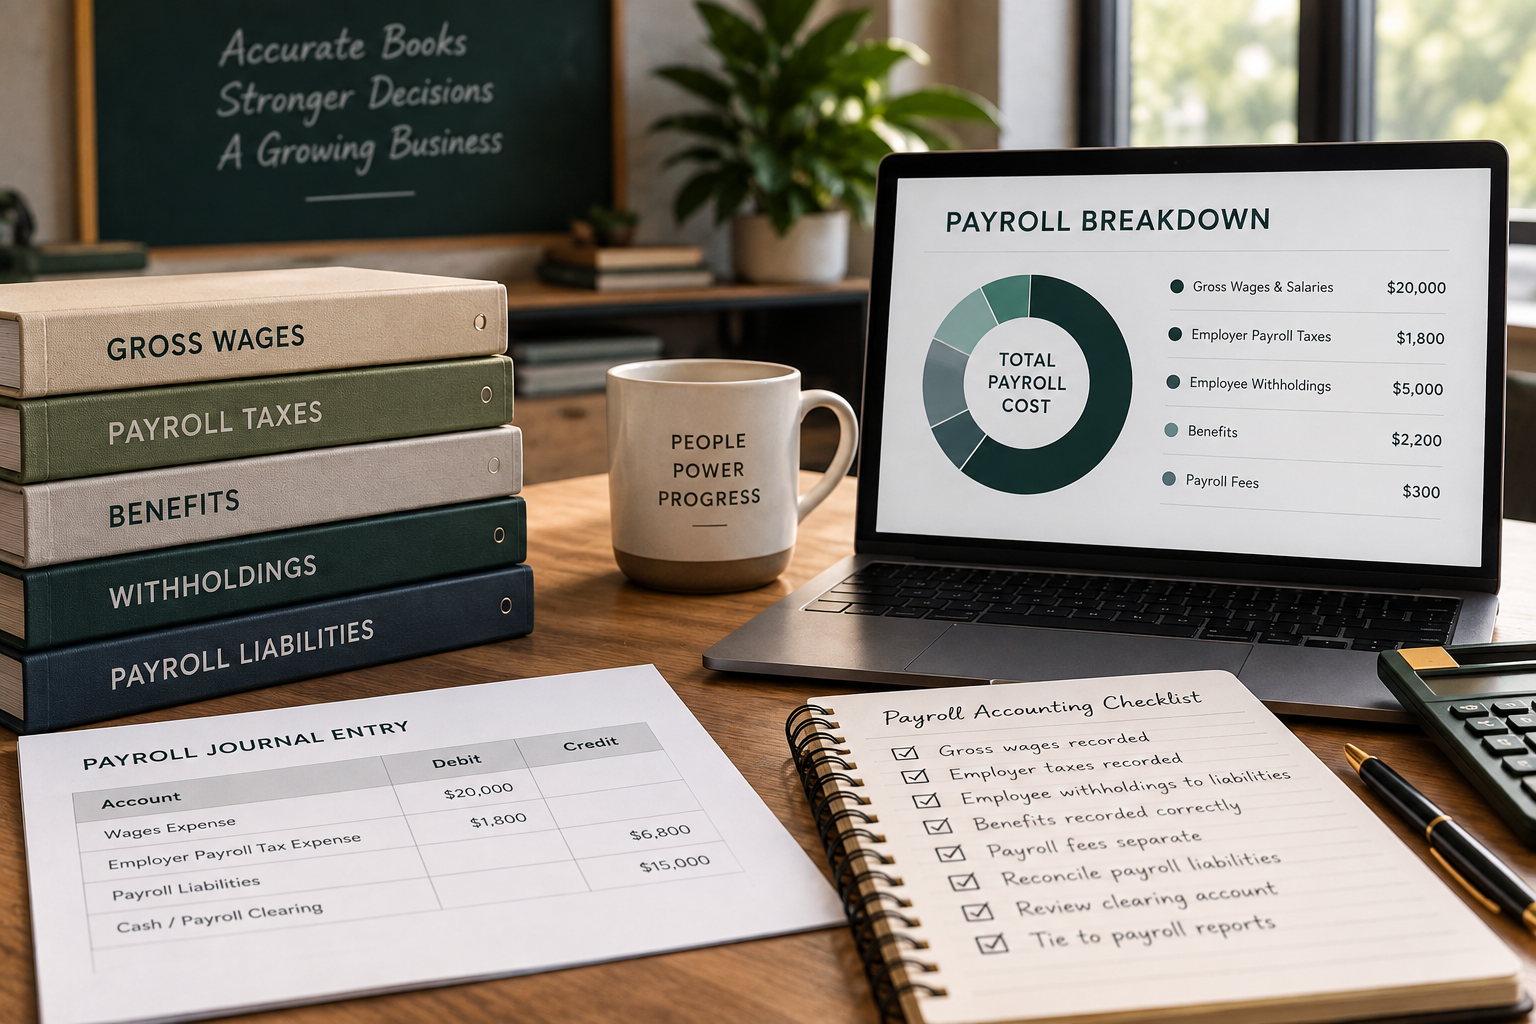
Payroll is often one of the largest expenses in a business.
It is also one of the most commonly misunderstood areas of accounting.
A payroll withdrawal may hit the bank as one lump sum. However, that does not mean your bookkeeper should record the entire amount as payroll expense.
Inside that payment are several different components, including employee wages, employer payroll taxes, employee withholdings, benefit deductions, retirement contributions, reimbursements, and other payroll-related costs.
If your accounting team does not separate those components correctly, your Profit & Loss statement can become distorted. At the same time, your Balance Sheet may carry payroll liabilities that do not accurately reflect what the company owes.
At Outgrow Accounting & Finance, we believe payroll accounting should do more than match the bank. Your books should clearly show what employees earned, what the company incurred, what the company owes, and what it actually paid.
To accomplish that, you need to understand what belongs on the P&L, what belongs on the Balance Sheet, and how those pieces connect.
Why You Should Not Record Payroll as One Expense
One of the most common payroll accounting mistakes happens when a business records the total cash withdrawal from its payroll provider as payroll expense.
In most cases, that treatment does not accurately reflect what happened.
Payroll contains both business expenses and amounts the company withholds or remits on behalf of employees.
For example, assume your company has $20,000 in gross payroll.
Employees may have deductions for:
- Federal income tax
- Social Security
- Medicare
- State income tax
- Health insurance
- Retirement contributions
- Garnishments or other deductions
Meanwhile, the business may also incur:
- Employer Social Security
- Employer Medicare
- Federal unemployment tax
- State unemployment tax
- Employer-paid health benefits
- Retirement contributions or matching
- Workers’ compensation or other payroll-related costs
Employees may ultimately receive only $15,000 in net pay.
However, the company’s payroll expense is not simply $15,000. Likewise, the total cash leaving the bank may exceed $20,000 once employer taxes and other payroll costs come into play.
Therefore, proper payroll accounting requires you to separate the different components.
What Should Go on the P&L as Payroll Expense?
The Profit & Loss statement should show the true labor cost the business incurred during the period.
Typically, that includes several categories.
Gross wages and salaries represent the full amount employees earned before deductions.
In addition, the company should record employer payroll taxes such as the employer portion of Social Security and Medicare, unemployment taxes, and other employer-paid payroll taxes.
Businesses may also need to record employer-paid benefits, including health insurance premiums, retirement contributions, employer matching, or other benefits.
Finally, compensation categories such as bonuses and commissions should appear in the appropriate section of the P&L.
The important distinction is this:
Employee withholdings do not create an additional payroll expense.
Instead, the company withholds those amounts from the employee’s gross wages and temporarily owes them to another party.
What Belongs on the Balance Sheet?
While the P&L shows payroll expenses, the Balance Sheet tracks payroll liabilities.
When the company processes payroll, it may owe money to tax agencies, benefit providers, employees, or other third parties before the cash actually clears.
Common payroll liability accounts include:
- Federal payroll taxes payable
- State withholding payable
- Social Security and Medicare payable
- Employee benefit deductions payable
- Retirement contributions payable
- Garnishments payable
- Payroll clearing
- Accrued payroll
For example, an employee may earn $5,000 in gross wages but receive only $3,800 in net pay.
The remaining $1,200 may consist of taxes and benefit deductions. Instead of disappearing, those amounts generally flow into payroll liability accounts until the company or payroll processor remits them to the appropriate agency or provider.
As a result, a clean Balance Sheet should clearly show any payroll obligations that remain unpaid at month-end.
Gross Payroll vs. Net Payroll
Understanding the difference between gross and net payroll is essential.
Gross payroll represents what employees earned before taxes and deductions.
Net payroll represents what employees actually receive after those deductions.
For accounting purposes, gross wages generally drive wage expense. Net payroll, on the other hand, represents the cash the employee receives.
The difference flows through payroll liabilities.
If your books record only net payroll as wage expense, you understate the true labor cost.
Consequently, several important financial metrics may become inaccurate, including:
- Gross margin
- Labor percentage
- Department profitability
- Job costing
- Budget performance
- Forecasting
- Pricing decisions
For labor-intensive businesses, the difference can materially change how management views profitability.
A Simple Payroll Accounting Example
Consider a payroll run with the following numbers:
Gross wages: $20,000
Employee taxes and deductions: $5,000
Net pay: $15,000
Employer payroll taxes: $1,800
The business incurs $21,800 in wage and employer tax costs.
However, the accounting team should not simply record:
Payroll Expense: $21,800
Instead, a simplified payroll journal entry might include:
Debit: Wage Expense — $20,000
Debit: Employer Payroll Tax Expense — $1,800
Credit: Payroll Liabilities — $6,800
Credit: Cash or Payroll Clearing — $15,000
The exact journal entry will vary depending on the payroll provider, benefits, tax withdrawals, and timing of payments.
Still, the principle remains the same: separate the expenses from the liabilities and cash activity.
What Is a Payroll Clearing Account?
A payroll clearing account can make payroll accounting much easier to manage.
Think of it as a temporary holding account that connects the payroll reports to the withdrawals appearing in the bank.
First, the accounting team records the payroll journal entry against the clearing account. Then, as the actual payroll withdrawals hit the bank, they match those withdrawals against the clearing balance.
For example, a payroll provider may withdraw money separately for:
- Employee net pay
- Payroll taxes
- Benefits
- Retirement contributions
- Payroll processing fees
Instead of trying to make each bank withdrawal directly equal an expense, the clearing account creates a bridge between the payroll report and the bank activity.
Once the company records and pays everything correctly, the payroll clearing account should generally return to zero or carry a clearly explainable timing balance.
How Should You Record Payroll Processing Fees?
Payroll processing fees do not represent employee wages.
Therefore, businesses should generally record them as a separate operating expense.
Depending on the chart of accounts, you might use:
Payroll Processing Fees
or
Payroll Service Fees
Separating these costs makes the P&L more useful because management can distinguish the cost of labor from the administrative cost of processing payroll.
What About Employee Reimbursements?
Employee reimbursements also require separate consideration.
For example, an employee may receive reimbursement for:
- Mileage
- Travel
- Office supplies
- Meals
- Business purchases
Even if the payroll provider includes the reimbursement in the employee’s paycheck, the accounting team should generally record the amount according to the underlying business expense.
In other words, the payment method does not determine the accounting treatment.
The purpose of the transaction does.
Therefore, a mileage reimbursement should not automatically increase wage expense simply because payroll delivered the payment.
How Should Payroll Be Recorded in QuickBooks?
The best process depends on your payroll provider and how it integrates with QuickBooks.
Some payroll systems send detailed journal entries directly into QuickBooks. Others primarily send bank transactions, which means the accounting team may need to record payroll manually.
Regardless of the method, your payroll accounting should allow you to identify:
- Gross wages
- Employer payroll taxes
- Employee tax withholdings
- Employer-paid benefits
- Employee deductions
- Net pay
- Payroll service fees
- Payroll liabilities
- Cash or payroll clearing
The goal is not to make payroll accounting unnecessarily complicated.
Instead, the goal is to make sure your financial statements reflect the true economics of payroll.
Should Payroll Be Broken Out by Department or Labor Type?
For many businesses, the answer is yes.
One large account labeled Payroll Expense often does not provide enough information for meaningful financial analysis.
Depending on the company, management may benefit from separating payroll into categories such as:
- Direct labor
- Administrative payroll
- Sales payroll
- Management salaries
- Production labor
- Delivery labor
- Payroll taxes
- Benefits
In addition, some payroll belongs in Cost of Goods Sold or Cost of Services, while other payroll belongs in Operating Expenses.
That distinction can materially affect gross profit and operating margin.
For example, a restaurant may want to separate kitchen labor from administrative wages. A construction company may track field labor separately from office employees. Likewise, a manufacturer may include production labor in Cost of Goods Sold.
Ultimately, the right structure depends on how management needs to understand the business.
When Should Payroll Go Into Cost of Goods Sold?
Not every payroll expense belongs below gross profit.
If employees directly produce the product or deliver the service the customer purchases, some labor may belong in Cost of Goods Sold or Cost of Services.
Proper classification gives owners better visibility into:
- Gross margin
- Labor efficiency
- Contribution margin
- Job profitability
- Service-line profitability
For example, suppose a service company generates $100,000 in revenue and spends $40,000 on employees who directly deliver that service.
If the company records that $40,000 entirely as an operating expense, gross profit may appear much stronger than the economics of the business actually support.
By contrast, placing direct labor in the appropriate cost-of-sales section helps management understand what it truly costs to generate revenue.
Why Should You Reconcile Payroll Liabilities?
Payroll liabilities should never become a collection of unexplained balances on the Balance Sheet.
As part of the monthly close, your accounting team should compare payroll liability accounts with supporting payroll reports and tax records.
For instance, a growing payroll tax liability may signal that:
- The company has not recorded tax payments
- Taxes remain unpaid
- Payroll journal entries are incomplete
- Someone duplicated a liability
- The payroll system posted information incorrectly
Of course, a payroll liability balance is not automatically a problem. Timing differences can create legitimate balances at month-end.
However, someone should always be able to explain what makes up the balance.
What Reports Should Support Payroll Accounting?
Good payroll accounting starts with good supporting documentation.
Your accounting team should retain the reports needed to support each payroll journal entry.
Depending on the payroll provider, these may include:
- Payroll summary
- Payroll detail
- Payroll register
- Payroll tax liability report
- Tax payment report
- Benefit deduction report
- Employer contribution report
- Payroll journal
- General ledger detail
These reports allow the accounting team to prove that the payroll journal entry agrees with the payroll system.
Furthermore, maintaining the documentation makes future cleanup, CPA review, and audit support significantly easier.
How Often Should Payroll Be Reconciled?
Businesses should review payroll activity during each pay period and reconcile payroll-related Balance Sheet accounts every month.
As part of the month-end close, the accounting team should confirm that:
- Payroll journal entries agree with payroll reports
- Net pay agrees with bank withdrawals
- Payroll tax payments cleared
- Benefit payments were recorded correctly
- Payroll liabilities are reasonable
- Payroll clearing accounts are resolved
- Payroll fees are categorized separately
- Gross wages agree with payroll reports
By reviewing these items monthly, businesses can identify problems while the information is still fresh.
Waiting until year-end often turns a small payroll issue into a much larger cleanup project.
How Can a Business Owner Tell Whether Payroll Is Recorded Correctly?
Business owners do not need to recreate every payroll journal entry.
However, they should know what questions to ask.
Start with the P&L. Does it show gross wages, or does it appear to reflect only net payroll?
Next, review employer payroll taxes. Your financial statements should distinguish employer tax expense from employee tax withholdings.
Then look at the Balance Sheet. Payroll liabilities should appear when the company owes payroll taxes, benefits, retirement contributions, or other payroll-related amounts.
You should also review the payroll clearing account. Ideally, it should return to zero after the payroll cycle finishes, or your accounting team should be able to explain any remaining balance.
Finally, consider where labor appears on the P&L. If the business relies heavily on labor to produce its product or deliver its service, putting every employee below gross profit may prevent you from seeing the company’s true margins.
These questions give owners meaningful oversight without requiring them to become payroll accountants.
Payroll Accounting Is About More Than Matching the Bank
Clean payroll accounting should tell you much more than how much money left your checking account.
It should clearly explain:
What employees earned.
What the company incurred.
What the company owes.
What the company paid.
What portion represents taxes and benefits.
Where labor belongs on the P&L.
When you structure payroll accounting correctly, your financial statements become much more useful.
As a result, you can better understand labor costs, gross margin, profitability, and cash flow.
At Outgrow Accounting & Finance, we help business owners clean up payroll accounting, reconcile payroll liabilities, structure payroll appropriately on the P&L, and build month-end processes that produce more useful financial reporting.
Payroll is too significant to record as one lump-sum expense and move on.
Your books should show what payroll actually costs your business.
Leave a Reply